Trending

December has a way of turning a €40 gift into a €70 afternoon. You buy the present, then a card, then wrapping paper, then a coffee because you are in town anyway, then you spot something for your sister. None of it feels reckless at the time. By 2 January, the damage is a pile of small, thoroughly reasonable decisions.
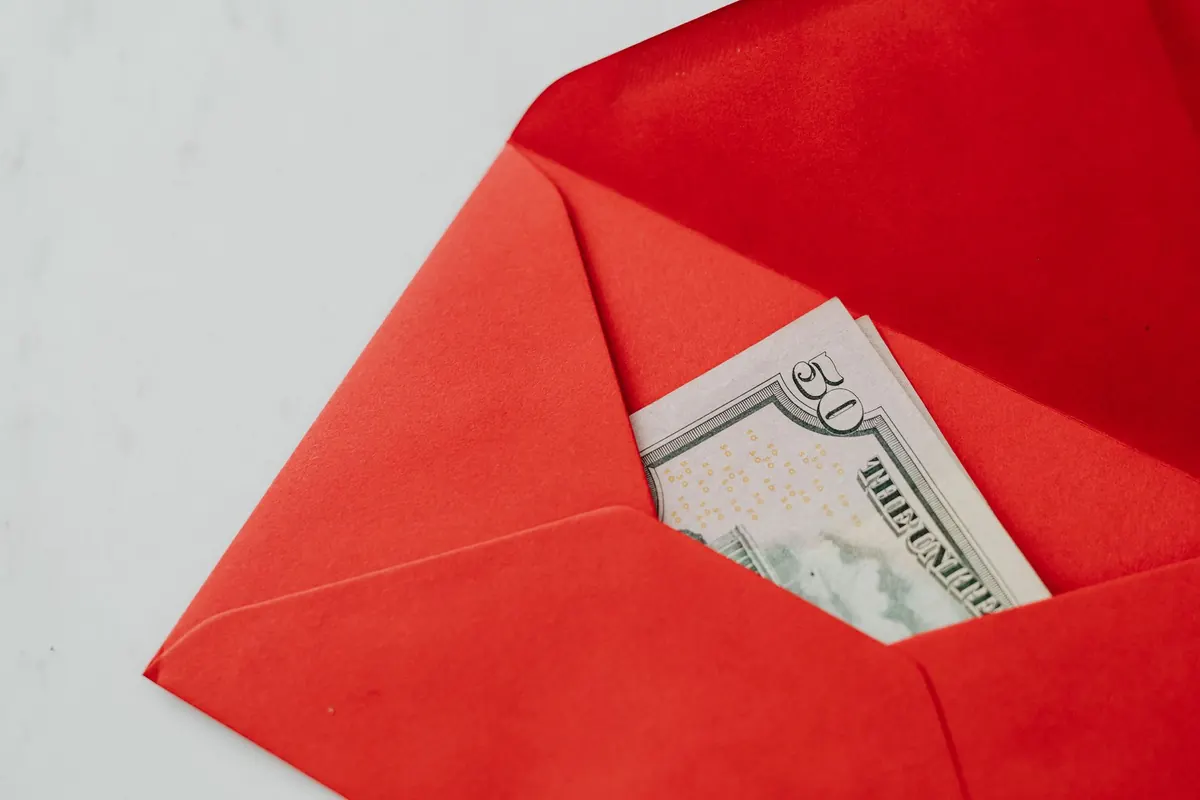
A cash envelope budget is unglamorous, and that is precisely why it works. You decide in November what December is allowed to cost, withdraw that money, divide it into labeled envelopes, and spend only from those envelopes. When the gift envelope is flat, gift shopping is finished. Here is how to set it up without turning the holidays into an accounting exercise.
Card payments are frictionless, and friction is the thing most people are short of in December. Cash restores it. Handing over five notes for a present feels different from tapping a phone, and that small hesitation is where real decisions get made.
Cash also makes your limit visible. A bank balance can look healthy on 12 December while three direct debits and a fuel bill are still waiting to land. An envelope cannot lie to you. The money in your hand is money that is actually available.
One caveat: keep the rest of your finances running normally. Rent, utilities and debt payments should not pass through envelopes. Pay those first, then fund December from what is left. If money is genuinely tight this year, or you are carrying high-interest debt, a short conversation with a qualified financial adviser is worth more than any budgeting trick.
Most December budgets fail at the start, because they cover gifts and nothing else. Gifts are usually less than half the cost of the month.
Go through last December's bank statement if you can face it. It will give you a truer number than your memory will.
Pick a total you can pay in cash without touching savings you need or borrowing. Subtract your estimates and see what is left over. If the list costs more than the total, the list has to change now, not on 19 December when you are tired and standing in a queue.
Five to seven envelopes is the useful range. More than that and you spend the month shuffling paper.
Label them plainly: Gifts, Food, Travel, Events, Extras. Put the calculated amount into each one and write the figure on the front so you can watch the envelope get thinner. Keep the Extras envelope small but not zero. It is the pressure valve that stops you raiding the gift money when a neighbour turns up with a present you did not expect.
If cash is impractical for you, a prepaid card or a separate account with the same sub-limits will do the job — but be honest about which one you will actually respect.
Work from people inward, not shops outward. Write the names down, give each one a number, add them up. Then cut.
Children are a different matter, and many families find a version of "something they want, something they need, something to wear, something to read" far easier to hold to than an open-ended list.
The calendar is what separates a plan from a wish. Each week has a job and a spending window.
It will happen, usually to the food envelope around the 20th. The rule is that envelopes do not borrow from each other without a decision. Move money deliberately, in daylight, from a category you are willing to cut, and say so out loud to whoever shares the budget.
What you do not do is top up from a card and promise yourself you will sort it out in January. That is how a December budget becomes a January problem.
Get the total, list the names, withdraw the cash, write on the envelopes, put the calendar on the fridge. Forty minutes of dull work in late November buys you a December where the final week does not feel like a scolding.
Money advice is general and your circumstances are specific. If your income has changed or your debts are growing, speak to a qualified adviser before you fix the total.